Ranked #20 of 74 · Updated October 2026
Nexo review
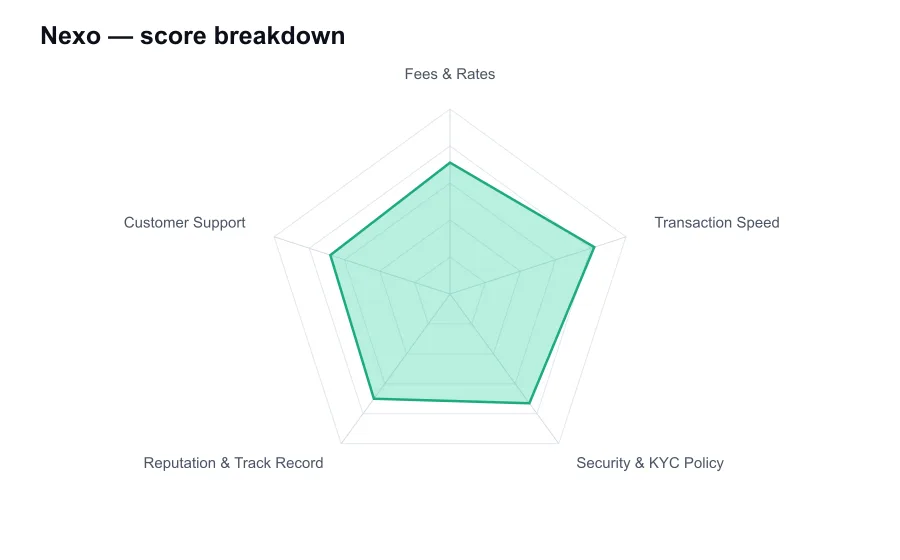
Nexo scores 7.3/10 overall in our independent review, measured against every other provider we've compared, strongest on Transaction Speed (8.2/10) and weakest on Customer Support (6.8/10).
Crypto backed credit lines · Nexo Pro trading · Crypto rewards and loyalty tiers · Card in supported regions
Nexo is a centralized digital asset platform built around a simple pitch: hold crypto, borrow against it, swap it, and in eligible cases earn yield without moving between several apps. It occupies a different corner of the market from a plain exchange. The company wants to be a crypto wealth platform, and that ambition makes it more useful than a basic broker but also more complicated and more exposed to counterparty risk.
Founded in 2018, Nexo grew during the lending boom by offering credit lines secured by crypto and interest bearing accounts for deposited assets. Its product has survived longer than many lenders from that era, which deserves recognition after the failures of Celsius, BlockFi, Voyager, and others. Survival is not proof that a platform is risk free. It does mean Nexo has been tested by the ugly side of the industry rather than only by rising markets and easy deposits.
The app is polished. A user can buy or exchange supported assets, use them as collateral, repay a loan, and track portfolio value without the intimidating feel of an advanced trading terminal. Nexo also offers a card in supported regions and a loyalty structure tied to holding its NEXO token. That design is attractive to people who want one dashboard. It is less appealing to purists who prefer separating custody, trading, lending, and spending so that one company's failure cannot affect every function.
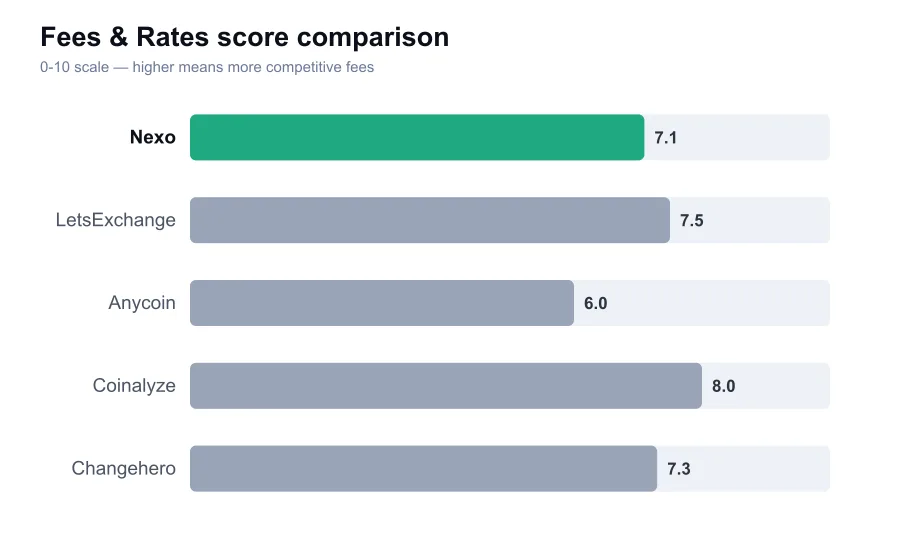
Fees depend heavily on which part of Nexo you use. The retail exchange generally works through a quoted conversion rate rather than a visible order book, and Nexo has historically disclosed a spread of up to 0.5 percent on swaps. This is convenient but not automatically cheap. On liquid pairs, a major spot exchange can often beat the all in price. Nexo Pro is the better venue for users who want conventional trading, with published maker and taker pricing that has been advertised from roughly 0.04 percent maker and 0.06 percent taker at the entry tier.
That difference matters. Buying Bitcoin once a month through the main app may be perfectly reasonable if convenience is worth a few tenths of a percent. Rebalancing a portfolio every week through spread based swaps can become expensive without looking dramatic on any single transaction. The same warning applies to card and third party purchase methods, which may add their own processing cost. Check the final amount of crypto received, not just the word fee on a screen.
Borrowing is where users can make the most expensive mistakes. Nexo credit is collateralized, and the interest rate depends on the asset, loan to value ratio, loyalty tier, and whether interest is paid in NEXO tokens. Promotional rates can look compelling, but a loan against volatile collateral is never free money. If collateral falls sharply, the platform can require more collateral or liquidate assets according to its terms. That is the central risk, and no elegant app design changes it.
Speed is usually a strength. Internal transfers, swaps, and loan actions are processed rapidly because they happen in Nexo's own ledger. Card transactions, where available, are designed for normal payment speed. Deposits and withdrawals depend on the blockchain and on compliance checks, but major network transfers are commonly processed within a practical timeframe. The catch is that speed vanishes if an account triggers source of funds questions or enhanced verification. That is normal compliance behavior, yet it can be deeply inconvenient during a volatile market.
Nexo is not a no KYC service. Full use requires personal verification, and the company can ask for additional documents related to income, wealth, or a specific transaction. People who resent that should avoid it rather than joining and discovering the policy later. Centralized lending requires the platform to know who its customers are, particularly in the jurisdictions it serves. The verification process also makes the service a poor choice for anyone whose priority is private, permissionless use of crypto.
The company has made security a major part of its public case, citing custodial arrangements, cold storage practices, insurance related protections, and security standards. Nexo has also referred to real time asset attestation arrangements, although customers should read carefully what an attestation does and does not establish. It is not the same thing as a full independent audit of every liability, every operational control, and every legal claim. The strongest security practice for a user remains modest exposure and self custody for coins not actively being used.
Nexo's track record is better than its loudest critics often admit. It weathered the 2022 contagion that destroyed several competitors and continued to operate. At the same time, its history includes serious regulatory pressure, including a settlement with US state regulators in 2023 related to its Earn Interest Product, followed by a wind down of that product for US clients. The platform also exited the United States retail market. Those facts should discourage anyone from treating its yield products as equivalent to an insured savings account.
The NEXO token deserves separate scrutiny. Higher loyalty tiers can improve borrowing rates, yields, and platform benefits, but holding a company linked token adds correlated risk. If confidence in Nexo weakens, the token and the service can both suffer at the same time. A small allocation may make mathematical sense for a user who knows exactly how the tier calculation works. Building a large NEXO position solely to chase a slightly better advertised rate is a gamble dressed up as loyalty.
Support is more capable than at many small exchanges, with help center material, ticketing, and live chat availability advertised for users. Basic questions are usually easy to route. The hard cases are account reviews, collateral disputes, and delayed withdrawals, where customers naturally want a named person and a definite deadline. Reports from users are mixed, as they are across centralized finance. Nexo's support is serviceable, but nobody should borrow against volatile assets on the assumption that support can solve a liquidation crisis after it starts.
Nexo compares favorably with failed crypto lenders simply because it is still functioning and has diversified its product set. Against Kraken or Coinbase for straightforward spot buying and self directed custody, it is less transparent and less cleanly separated. Against DeFi lending, it is far easier to use but requires faith in a company, its legal structure, its risk management, and its access to banking. That trade is the whole product, not a minor detail buried in the terms.
I think Nexo is best used selectively. Its exchange and credit tools can be useful for experienced crypto holders who understand collateral ratios, do not overborrow, and keep their exposure limited. It is not a substitute for a bank account, a cold wallet, or a diversified broker. The platform has proven more resilient than many peers, but the right response to that resilience is measured confidence, not blind trust.
Who it suits
Nexo suits experienced holders who want a centralized credit line or a compact portfolio management app. It can also work for users who trade on Nexo Pro and understand how loyalty tiers alter pricing. Beginners should avoid borrowing against volatile coins until they understand liquidation mechanics. Anyone wanting private access, insured cash savings, or direct control of keys should choose other tools.
The practical view
Strengths and trade-offs
What stands out
- Integrated lending, exchange, and card ecosystem
- Nexo Pro offers low published trading fees
- Survived the 2022 crypto lending crisis
- Fast internal portfolio actions
What to weigh
- Retail swaps may include a meaningful spread
- Collateral loans can trigger liquidation
- NEXO loyalty tiers add token concentration risk
- Not available for US retail customers
Scorecard
How the score is built
Verdict
My take on Nexo
Nexo is one of the more credible survivors of crypto lending's painful cleanup, and that counts for a lot. Its best features are the smooth interface, quick internal operations, and a broader product range than a basic exchange. The problem is structural rather than cosmetic: deposits and collateral live within a centralized company whose risk decisions you cannot inspect completely. Use Nexo for a defined purpose, not as the place where every digital asset and every spare dollar should live.
Review questions
Nexo FAQ
What does Nexo charge for crypto exchanges?
The main app commonly uses a quoted rate that can include a spread of up to 0.5 percent. Nexo Pro has a separate maker and taker fee schedule.
Can Nexo liquidate my crypto?
Yes. If a collateralized loan breaches the platform's loan to value requirements, Nexo can sell collateral under its terms to reduce the outstanding debt.
Is Nexo available in the United States?
Nexo wound down its US retail business. Availability and individual products depend on your country, so check the current eligibility page before depositing.
Reader experiences
What users report
Continue your comparison
Read across the full ranking before deciding which provider best fits your own needs.
Compare providers