Ranked #68 of 74 · Updated October 2026
ClickPay review
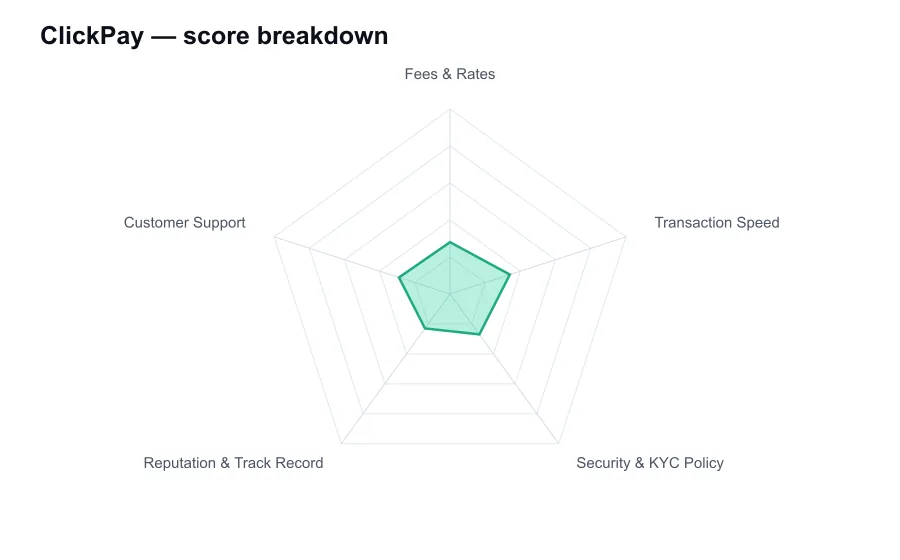
ClickPay scores 2.8/10 overall in our independent review, measured against every other provider we've compared, strongest on Transaction Speed (3.4/10) and weakest on Reputation & Track Record (2.3/10).
Payment-oriented branding · Merchant-checkout potential · Verification required · Not recommended for crypto custody
ClickPay is a name used by more than one payments-related business, which creates a basic but important problem for crypto users: brand ambiguity. A payment processor, a merchant checkout product, and a crypto exchange are not interchangeable services, even if their names sound similar. I cannot confidently identify a single, well-established crypto exchange operation called ClickPay with the public depth needed for a conventional exchange review. That uncertainty is not a minor footnote. It is the starting point for any responsible assessment.
If you encountered ClickPay through an advertisement, a direct message, a merchant payment page, or a crypto promotion, slow down before connecting a wallet or sending funds. Confirm the exact legal entity, official domain, terms of service, supported jurisdictions, and product type. Fraudsters regularly exploit generic payment names because users may assume a familiar-sounding brand is a known financial institution. A name alone is not evidence of licensing, custody standards, or a legitimate exchange operation.
The first thing I would ask is whether ClickPay actually executes crypto trades, merely facilitates card or bank payments, or acts as a front end to another provider. Each model has different costs and risks. A true exchange should disclose its trading fees, withdrawal charges, supported networks, order execution method, custody arrangement, and complaint process. A payment gateway should explain merchant settlement, chargeback rules, card data protection, and any crypto partner involved. Without that clarity, no score for low fees can be treated as meaningful.
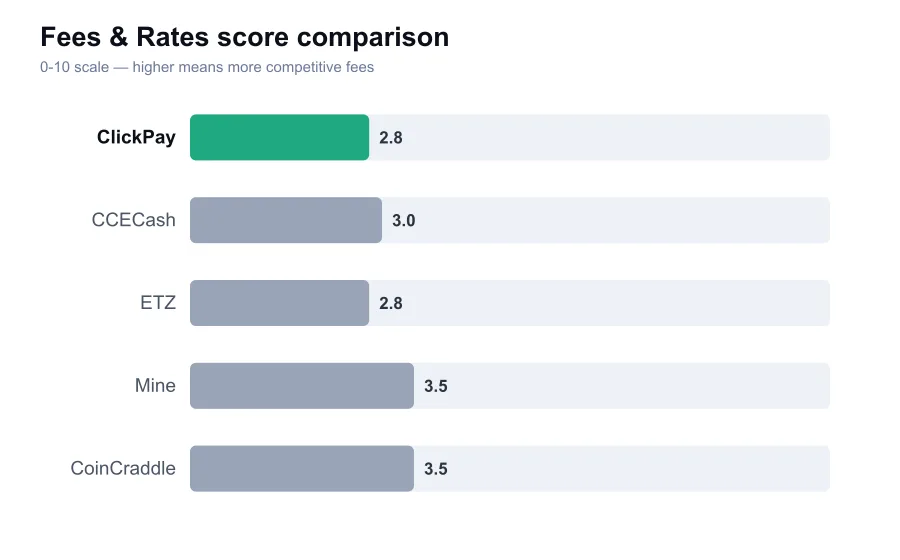
Pricing is therefore a serious weakness from a reviewer's perspective. Some payment products advertise convenience while stacking card processing charges, foreign-exchange margins, crypto conversion spreads, and blockchain withdrawal costs into a single opaque amount. The customer may see only the final total. That is not necessarily improper, but it is impossible to call competitive without a complete quote and a transparent explanation. I would not use ClickPay for a crypto purchase until I could see exactly what asset arrives, on which network, and what every layer costs.
Card-funded crypto purchases are especially prone to bad value. Even a legitimate provider may charge a card processing premium, while the bank can classify the transaction as a cash-like purchase and add its own fee or interest treatment. If ClickPay is offering card-to-crypto conversion, compare the final cost with buying through a bank transfer at a well-known exchange. The difference can easily outweigh the convenience of a faster checkout.
Speed should be judged with the same discipline. A card authorization can be instant, but crypto delivery may not be. The provider may wait for fraud checks, require additional verification, route the order through a partner, or wait for network confirmations before sending an asset. A merchant payment may be approved while settlement to the merchant takes longer. ClickPay should not be trusted with an urgent conversion or time-critical purchase until it has documented processing times and shown a record of meeting them.
Security claims are impossible to assess properly without a confirmed operator. A reputable financial or crypto service should publish a privacy policy, terms, corporate identity, security controls, and accessible support contact details. If it holds customer funds, stronger evidence is needed, including clear custody arrangements, account protection methods, and a realistic incident response process. A generic web page with a lock icon is not security due diligence. HTTPS protects the connection, not necessarily your money.
KYC policy deserves direct attention. Payment and crypto providers commonly collect identity details, card information, address data, and sometimes source-of-funds documents. That can be legitimate compliance practice, but customers need to know who receives the information and under which privacy rules. Never upload identification to a site whose legal entity and official domain you have not independently verified. A request for documents after money has been sent can turn an uncertain transaction into a much more stressful situation.
The reputation score here is low not because I have established misconduct by a particular ClickPay operator, but because the product identity itself is too ambiguous to support trust. There is no clear basis to compare a generic ClickPay crypto offering with named, widely reviewed exchanges. In financial services, lack of verifiability is a real negative. Users deserve more than a brand name and a payment button before they are asked to disclose personal data or transfer irreversible assets.
This ambiguity also makes customer support hard to evaluate. A reputable service should have a documented contact route, a clear support scope, and a reliable path for disputes. For card payments, there may be bank or card-network protections depending on the transaction. For crypto transfers, irreversible blockchain mechanics sharply reduce those protections. If ClickPay has no clearly attributable support team and no obvious formal complaint process, a user should simply not proceed.
There are a few checks that take very little time and can prevent a costly mistake. Search the exact domain, not only the brand name. Read the legal pages and match the company name against an official corporate registry where possible. Check whether the address, phone number, and email domain are consistent. Look for a real explanation of fees and supported countries. Then independently verify whether the business is authorized for the financial activity it claims to perform in your jurisdiction.
Be particularly suspicious if a ClickPay-branded service promises unusually high investment returns, asks you to pay a release fee before withdrawing crypto, offers support only through Telegram or WhatsApp, or pressures you to act immediately. Those are classic warning signs, not normal exchange behavior. A legitimate platform may use chat, but it should not rely on an untraceable messaging account as its sole means of customer service.
Could ClickPay be a legitimate payment tool in a narrow local or merchant context? Possibly, but that would require identifying the precise provider. It is not possible to transfer credibility from one similarly named business to another. Until the operating entity can be verified and its crypto capabilities are documented, treating ClickPay as a general-purpose exchange would be reckless. There are too many mature alternatives that do not require this level of guesswork.
My recommendation is blunt: do not use an ambiguous ClickPay-branded service for crypto storage, investment transfers, large purchases, or first-time card-to-crypto transactions. If you are dealing with a specific merchant checkout, confirm the merchant, payment processor, and refund terms before paying. For buying or swapping crypto, use a platform with a clearly identifiable operator, transparent pricing, published security policies, and an established track record. ClickPay has not supplied enough verifiable substance to earn more than a highly cautious, provisional assessment.
Who it suits
ClickPay is not a sensible choice for crypto investors, traders, or anyone transferring a meaningful amount. It may only be relevant where a specific, independently verified merchant uses a clearly identified ClickPay payment processor and the transaction terms are acceptable. Beginners should avoid it entirely until the exact entity is confirmed. Users seeking crypto purchases or swaps should choose a recognized exchange with published fees, security information, and accountable support.
The practical view
Strengths and trade-offs
What stands out
- May serve a narrow payment or merchant-checkout use case
- Generic payment branding can be familiar to users
- Could be convenient if the exact operator is verified
What to weigh
- No confidently identifiable crypto exchange operation
- Fees and settlement model are not reliably assessable
- Brand ambiguity creates phishing and impersonation risk
- Not appropriate for custody or major crypto transfers
Scorecard
How the score is built
Verdict
My take on ClickPay
ClickPay cannot earn a favorable exchange recommendation because the name does not reliably identify a single, transparent crypto provider. That is a fundamental trust problem, not a cosmetic issue. The potential upside of a convenient payment page is tiny compared with the downside of sending irreversible funds to the wrong or poorly documented service. Verify the exact business before any payment, and use an established platform for crypto activity. Until then, caution is the only responsible verdict.
Review questions
ClickPay FAQ
Is ClickPay a crypto exchange?
The ClickPay name is used in payments contexts and does not by itself confirm a single identifiable crypto exchange. Verify the exact website, legal entity, product terms, and regulated activity before sending funds or documents.
Can I safely buy crypto with a ClickPay card checkout?
Do not proceed until you know who processes the payment, the final crypto amount, the delivery network, refund rules, and all fees. Card purchases can include processor, bank, conversion, and withdrawal costs.
What should I do if a ClickPay site asks for a release fee?
Do not send an additional payment merely to unlock a withdrawal. Preserve records, contact your bank or card provider if applicable, and seek local fraud-reporting guidance. Release-fee demands are a serious warning sign.
Reader experiences
What users report
Continue your comparison
Read across the full ranking before deciding which provider best fits your own needs.
Compare providers